 PocketProof
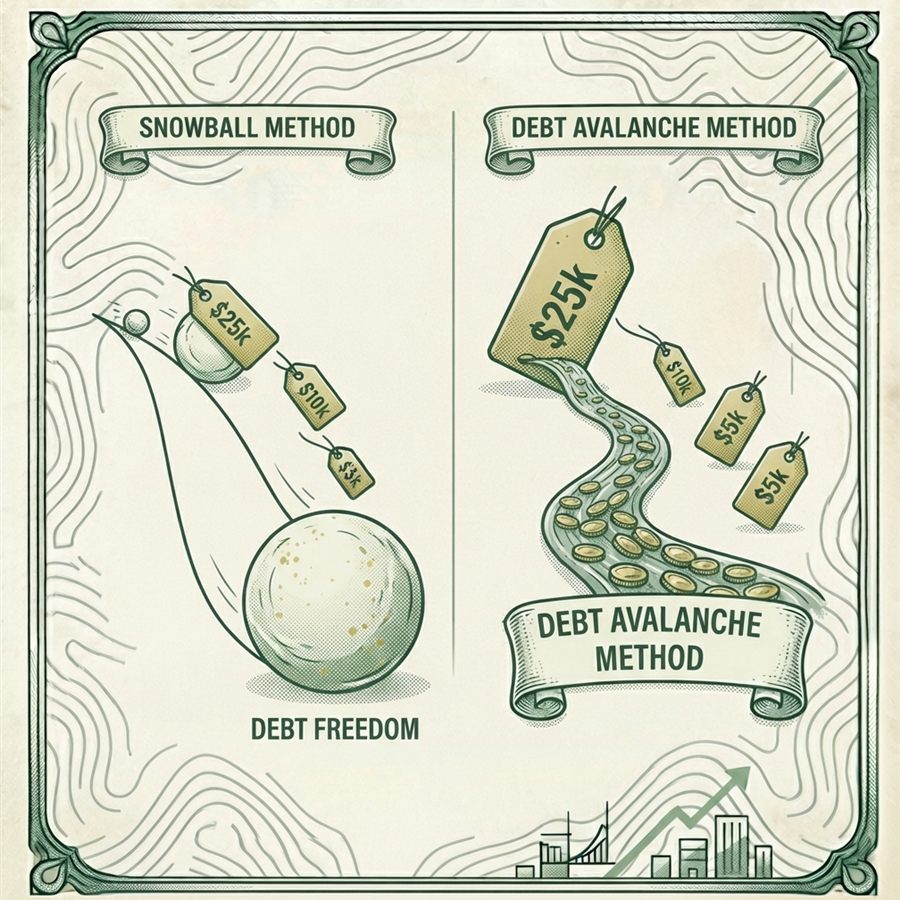
Both methods do the same basic thing: pay minimums on every debt, then throw all your extra money at one debt at a time until it's gone, then roll that payment into the next one. Where they differ is which debt you attack first, and that choice matters more for your motivation than your math.
The debt snowball: smallest balance first
List your debts from smallest balance to largest, ignoring interest rates. Put all extra payment toward the smallest one while paying minimums on the rest. Once it's paid off, roll its entire payment into the next-smallest debt. Repeat.
The appeal is momentum: you get a full payoff — an actual debt disappearing from your list — faster, which keeps motivation high during a process that can otherwise take years.
Total interest paid over 25 months, one worked example
$135.82 less in interest by attacking the highest-rate balance first — same 25-month timeline either way. Full example below.
The debt avalanche: highest interest rate first
List your debts from highest interest rate to lowest, ignoring balance size. Put all extra payment toward the highest-rate debt first, then move to the next-highest once it's cleared. Mathematically, this method minimizes the total interest you pay and gets you debt-free slightly faster overall.
Before you attack that highest-rate debt, it's worth a 15-minute phone call to see if you can lower the rate itself first — see our credit card APR negotiation script for the exact wording that works. And once a card is paid off, our first credit card guide covers the habits that keep it at $0.
A real numbers example
Say you have $200/month extra to put toward debt beyond minimums, across three balances: a $3,000 credit card at 24% APR, a $1,200 personal loan at 12%, and a $6,000 car loan at 7%. The two methods don't agree on where to start — snowball goes after the personal loan first (smallest balance), avalanche goes after the credit card first (highest rate) — and that disagreement shows up directly in the math.
Run the actual month-by-month numbers and both methods clear the debt in the same 25 months — but avalanche pays $1,156.97 in total interest versus snowball's $1,292.79, a real $135.82 saved by attacking the highest-rate balance first instead of the smallest one. Same payoff timeline, genuinely less money spent — that's the avalanche case in one example, not just in theory. The calculator below runs this on your own debts instead of a hypothetical.
| Method | Attack order | Months to debt-free | Total interest |
|---|---|---|---|
| Avalanche | Credit card → Personal loan → Car loan | 25 | $1,156.97 |
| Snowball | Personal loan → Credit card → Car loan | 25 | $1,292.79 |
Try it on your own debts
Enter your own balances, rates, and minimums below to see the real months-to-payoff and total-interest gap between the two methods — not a hypothetical.
Snowball vs. avalanche simulator
Defaults match the example above: a credit card, personal loan, and car loan with $200/month extra.
Assumes interest compounds monthly on the remaining balance and every freed-up minimum payment rolls into the next target debt. Estimates only — your real APR, fees, and due dates will shift the exact numbers.
The honest tradeoff
Avalanche is mathematically optimal. Snowball is behaviorally optimal for a lot of people. If you've started and abandoned debt payoff plans before, the quick wins from snowball are often worth more than the interest savings from avalanche — a plan you actually finish beats a theoretically better plan you quit in month four.
If guilt over how the debt happened is part of what's made past plans hard to stick with, see our guide on dealing with credit card guilt and building a realist's payoff plan — including an interactive worksheet that writes down exactly what to do on a month that doesn't go as planned.
How to choose
- Choose snowball if: you've tried debt payoff before and lost motivation, you have several small debts, or you know you're someone who needs visible progress to keep going.
- Choose avalanche if: you're motivated by the numbers themselves, one debt carries a much higher interest rate than the rest, or the interest savings between methods is large enough in your situation to matter (run both orders and compare — for high-rate debt like credit cards, the gap can be significant).
- Hybrid option: some people knock out one or two very small balances first for quick wins, then switch to avalanche order for the rest. There's no rule against it.
Not sure? Answer 3 questions
The simulator above tells you the numbers. This walks through the same decision the "How to choose" list just described, one honest question at a time.
Snowball, avalanche, or hybrid?
Answer honestly — this is about which plan you'll actually stick with, not which one is mathematically perfect.
Have you started and abandoned a debt payoff plan before?
Even knowing avalanche saves more in interest, does seeing a full payoff soon matter more to you than the math?
Is there a large interest-rate gap between your highest-rate and lowest-rate debt (e.g. a 24% credit card vs. a 7% car loan)?
Would a big interest-savings number motivate you more than an early payoff?
Do you have several small debts you could clear quickly?
Your answers point toward momentum mattering more than minimizing interest right now — list your debts smallest to largest and attack the smallest first. Run your real numbers in the simulator above to see exactly what that costs in extra interest.
Your answers point toward minimizing total interest mattering more than an early win — list your debts by interest rate, highest to lowest, and attack the highest-rate one first. Run your real numbers in the simulator above to see exactly what that saves you.
Your answers are split — a reasonable middle path is knocking out one or two of your smallest debts first for quick wins, then switching to avalanche order (highest rate first) for the rest. There's no rule against it.
Before you start either method
Make sure minimum payments on every debt are covered first — missing a minimum to accelerate another debt hurts your credit and can trigger penalty rates. And if you don't already have a small buffer set aside, build a starter emergency fund first; otherwise, the next unexpected expense becomes new debt and undoes your progress. Worth knowing exactly what "just the minimum" costs on its own — see our breakdown of the true cost of minimum payments.
Whichever method you choose, plug it into your monthly plan using zero-based budgeting so the extra payment is a real line item, not whatever happens to be left over at the end of the month.
Each debt this method clears is worth noticing on its own, not just the moment you're fully debt-free — see our guide on why small financial milestones deserve real celebration for why that actually matters to whether you finish the plan at all.
Want it to calculate the payoff date for you?
The PocketProof Budget System ($15) is an Excel & Google Sheets budget spreadsheet with a built-in debt payoff tracker — enter your balances and a payment amount, and it projects your payoff date automatically, snowball or avalanche.